By Lilia Nangong
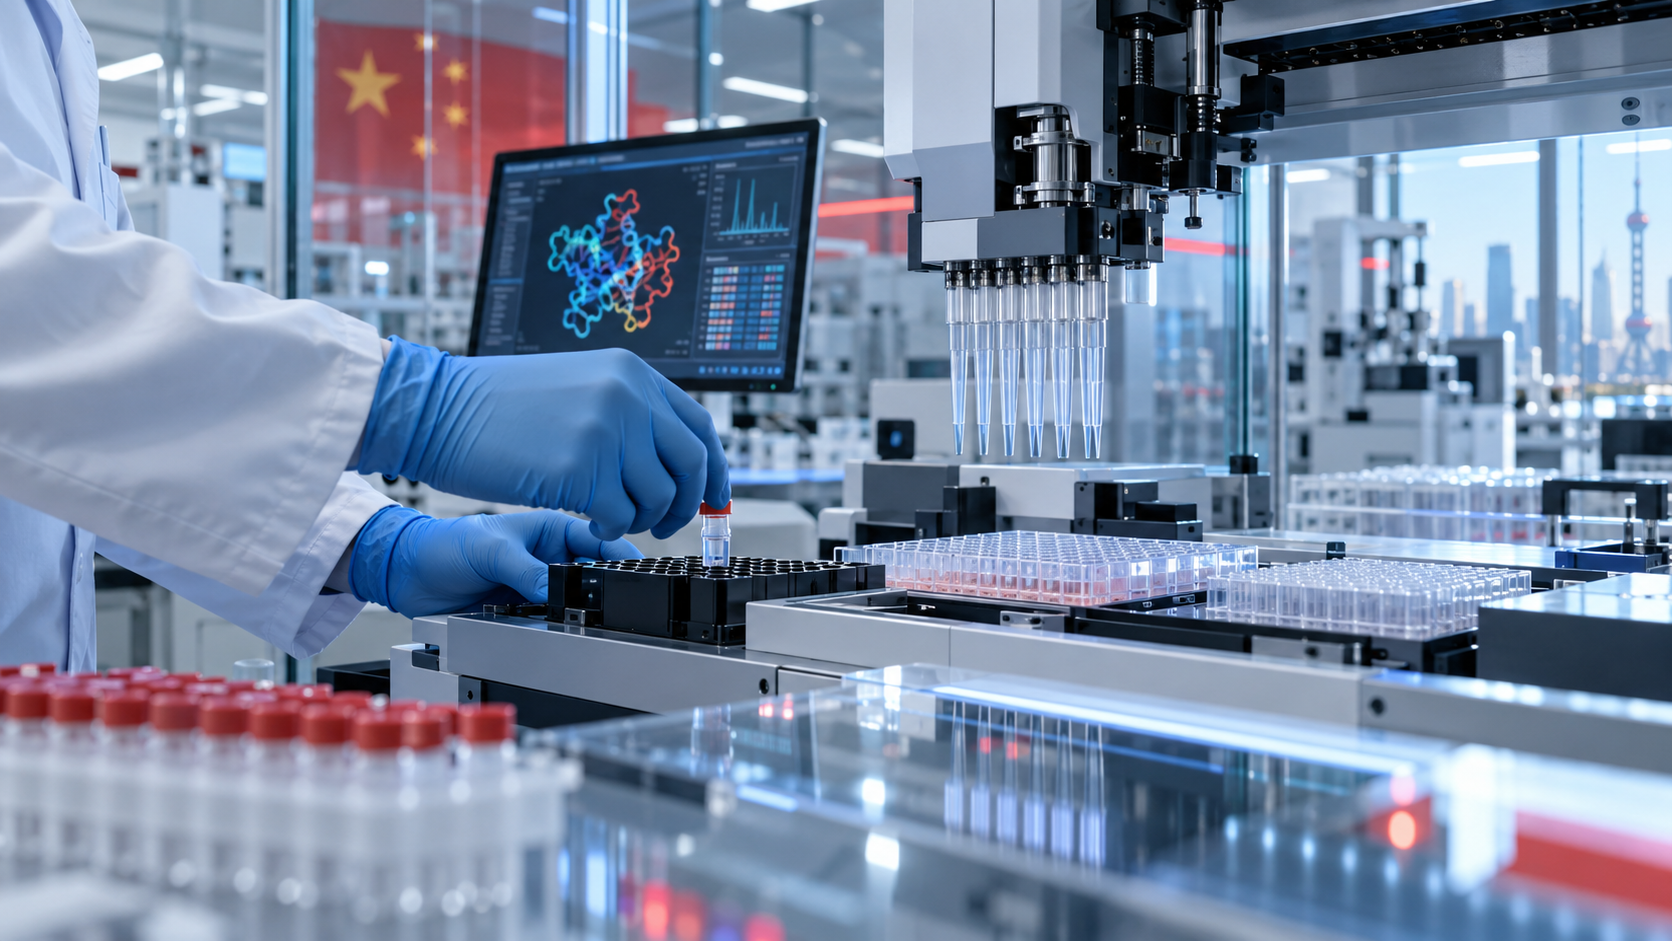
In June, the price of a single cynomolgus monkey on the Chinese market climbed to roughly $26,000, nearly double from a year earlier. The surge in demand for primates used in testing the safety of drugs is being driven by an expanding pipeline of next-generation therapies, such as antibody-drug conjugates, bispecific antibodies, and CAR-T, which are moving into first-in-human trials faster than the animals needed to test them can be bred.
While it’s a sign that China’s biotechnology sector is outgrowing its own infrastructure, the deeper story is that China’s bet on biotechnology is paying off faster than expected. Chinese firms are overtaking Western multinationals in new drug approvals in the U.S. and leading the world in the volume and speed of clinical trials.
Case in point: the average time to first-in-human testing in China is roughly one year, while in the United States it is closer to two to three.
That could explain why labs are running out of monkeys.
How China became a biotech powerhouse
China’s State Council named biotech a strategic priority more than a decade ago, and built the foundation of state funding, regulatory pathways, and manufacturing capacity to support it. China joined the International Council for Harmonization, aligning its standards with global norms of other regulators, like the U.S. Food and Drug Administration (FDA), and making its data credible to regulators abroad. Chinese regulators built innovator-friendly pathways that compressed development timelines. Venture capital flooded in during the late 2010s and left behind a durable capital base and a generation of companies trained to move fast.
China not only became a cheaper place to run trials, but also a world-class biotech innovation engine operating on a shorter clock than its Western counterparts.
Global capital and supply chains are already adjusting around that reality. Cross-border out-licensing of China-origin assets, negligible a few years ago, now runs into the billions annually. Western pharmaceutical firms are committing billions in direct investment, validating Chinese assets for global audiences, and transferring know-how in the process. Hong Kong is now positioning itself as a bridge market, listing Chinese biotech that need capital without the full burden of a U.S. IPO.
What the rise of Chinese biotech means for the world
The natural next question is whether Western patients will get better cures faster because of China’s biotech rise.
The honest answer: probably, but not as quickly as China’s growth suggests.
A larger pipeline and more trial sites raise the probability of breakthroughs, yet volume does not equal validated approvals. The FDA generally will not approve drugs based solely on single-country data from China, preferring multiregional trials or bridging studies. Many of the most promising Chinese therapies will still require additional, time-consuming work before reaching Western patients.
Western governments are reacting in ways that could tighten the regulatory bottleneck even more. In early August, U.S. Senators Elissa Slotkin and Pete Ricketts introduced the Biotech Investment National Security Act (BINSA), which would subject U.S. pharmaceutical licensing deals and equity investments in Chinese entities to outbound-investment review. The recent BIOSECURE Act already restricts federal agencies from contracting with certain Chinese biotechnology companies, treating Chinese biotech as a national security concern.
Whether common ground can be found remains to be seen. Governments in both hemispheres are now looking to artificial intelligence to shorten the controllable parts of the drug development timeline. China’s National Medical Products Administration issued implementation opinions on AI and drug regulation in April, targeting an integrated system by 2030, while the European Medicines Agency is under similar instruction through the EU Biotech Act.
What biopharma and investors need to know now
For U.S. biotech firms and investors, the current backdrop presents both significant opportunities and growing risks. Chinese counterparts offer attractive opportunities for asset diversification through out-licensing, partnerships, and M&A, particularly as U.S. pricing power erodes and margins compress. U.S. multinationals and venture capital firms are already actively pursuing opportunities upstream in the drug discovery process. At the same time, the U.S. regulatory environment governing outbound investment, licensing, and R&D collaboration with Chinese counterparts is becoming more restrictive, creating headwinds for both existing and prospective collaborative endeavors.
While some of this risk is being mitigated by innovative fundraising vehicles offered by Asian fund managers, which allow U.S. entities to maintain exposure while remaining compliant with applicable regulations, biotech companies and their investors seeking to straddle the Chinese and U.S. markets must navigate this environment with a careful public relations and risk-mitigation strategy.
First, identify chokepoint risks across the supply chain. Whether or not the current U.S. policy trajectory continues, the BIOSECURE Act has officially put biotechnology on the national security radar, while the Department of Defense’s 1260H List provides additional enforcement mechanisms that could affect the supply chain. During the five-year safe harbor stipulated by the Act, firms should map exposure across Active Pharmaceutical Ingredients (APIs), Key Starting Materials (KSMs), and processes ranging from front-end discovery through late-stage development and manufacturing to identify potential points of regulatory scrutiny. Investors, in particular, must incorporate chokepoint risks into their existing valuation and investment decision-making frameworks.
Second, prepare narrative contingency plans for potential government investigations and media scrutiny to maintain control of the public narrative. Chinese biotech firms and contract development and manufacturing organizations (CDMOs) vary considerably in their proximity to Beijing and their exposure to U.S. markets. WuXi, for example, has emphasized its independence following its designation on the Entity List in 2020, highlighting that two-thirds of its revenue comes from the U.S. market and its close cooperation with Eli Lilly. Chinese biotech companies are often lumped together in the public narrative as a singular national security threat. U.S. and their Chinese biopharma partners should proactively prepare messaging to address potential reputational challenges and distinguish individual companies based on their ownership, operations, governance, and exposure to the Chinese government.
Third, stress-test supply chain resilience based on potential regulatory restrictions. U.S. regulatory policy could continue to become more restrictive; the proposed BINSA would impose restrictions on investment, while language in the FY2027 FDA appropriations bill would bar the acceptance of certain Chinese clinical trial data. Maintaining up-to-date intelligence on legislative and regulatory developments is crucial for stress-testing business assumptions and recalibrating communications accordingly.
So, what do the monkeys (or lack thereof) tell us? China’s biotech maturation is here. The question is no longer whether to treat Chinese biotech as a future competitor or partner. It is how to realistically adapt to a market in which China’s biotech pipeline is already reshaping the global biotechnology landscape.